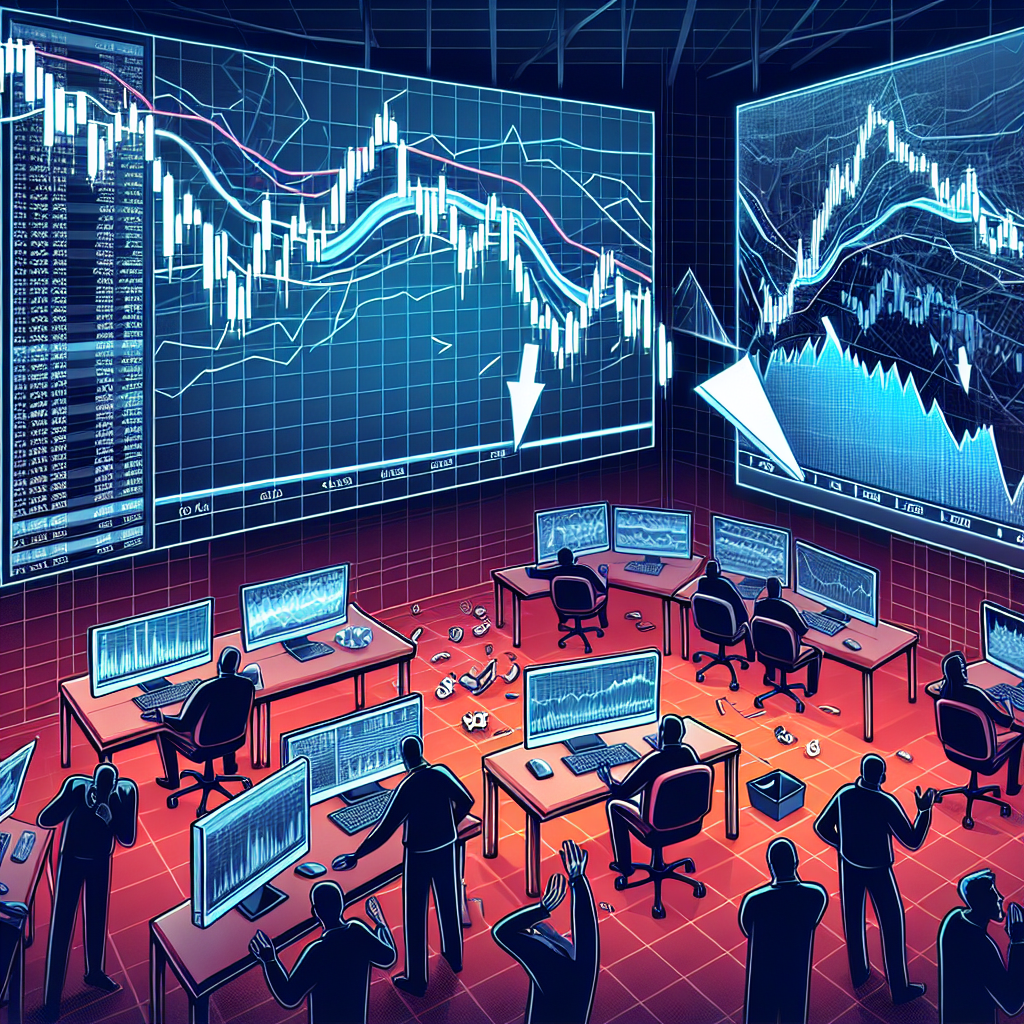
How trading algorithms can trigger flash crashes: using agent-based modeling and Monte Carlo simulations, market scenarios can be recreated where small disturbances are amplified until they generate rapid and deep price drops. These methodologies make it possible to explore the emergent dynamics when multiple agents with heterogeneous rules interact in microseconds and help identify parameter combinations that raise systemic risk.
In modeling experiments, three key parameters show a disproportionate impact on the severity of flash crashes: aggressive sell volume, trading frequency, and the inventory limits of market makers and algorithms. Sell volumes concentrated in short time windows can drain available liquidity; a very high trading frequency accelerates negative feedback between algorithms; and inventory limits that are too strict or poorly calibrated force liquidity providers to withdraw when they are needed most.
Monte Carlo simulations make it possible to quantify probabilities and outcome distributions by sampling scenarios with noise in the market signal, variations in latency between participants, and sudden changes in market depth. In this way, it is observed that overly aggressive algorithmic strategies, speed discrepancies between traders, and the absence of dynamic inventory management amplify the probability and magnitude of a flash crash.
A recurring finding is that there is no single universal trigger but rather a confluence of factors: algorithms that adjust orders in cascade, latency networks that generate asymmetries in information, and risk rules that cause simultaneous exits. Agent-based modeling also reveals contagion effects between correlated assets and shows how feedback signals can transform local shocks into systemic events.
The practical conclusions point to mitigation measures that can be adopted by both participants and regulators. These include active inventory management policies, rate limits for high-frequency orders, granular circuit breakers, throttling mechanisms for massive orders, and Monte Carlo-based stress tests as part of the algorithm validation cycle. These measures reduce the probability of algorithmic cascades and improve market resilience.
Q2BSTUDIO is a custom software and application development company specialized in building solutions that integrate artificial intelligence and cybersecurity for trading and analytics environments. We offer custom software, custom applications, and consulting services to design AI agents that monitor anomalous patterns in real time, implement risk management systems, and deploy secure cloud architectures with AWS and Azure cloud services.
Our services include business intelligence services and solutions with Power BI for data visualization and operational dashboards, as well as AI projects for companies that combine predictive models, backtesting through Monte Carlo simulations, and autonomous AI agents for execution and supervision. Our cybersecurity expertise ensures that platforms support access controls, encryption, and incident response, reducing the risk surface against algorithmic failures.
If your goal is to prevent flash crashes or improve the robustness of trading systems, Q2BSTUDIO can design custom software that implements dynamic inventory limits, intelligent throttling, alerts based on risk models, and Power BI dashboards for real-time monitoring. We combine artificial intelligence, AI agents, and AWS and Azure cloud services to deliver scalable and secure solutions that optimize operations and protect the market against unexpected shocks.
Contact Q2BSTUDIO to evaluate your architecture, run Monte Carlo simulations tailored to your operations, and develop custom applications that mitigate risks and improve operational resilience. Our capabilities in artificial intelligence, cybersecurity, business intelligence services, AI for companies, and Power BI allow us to transform regulatory and risk requirements into robust and scalable technical solutions.